Impact of One Late Payment
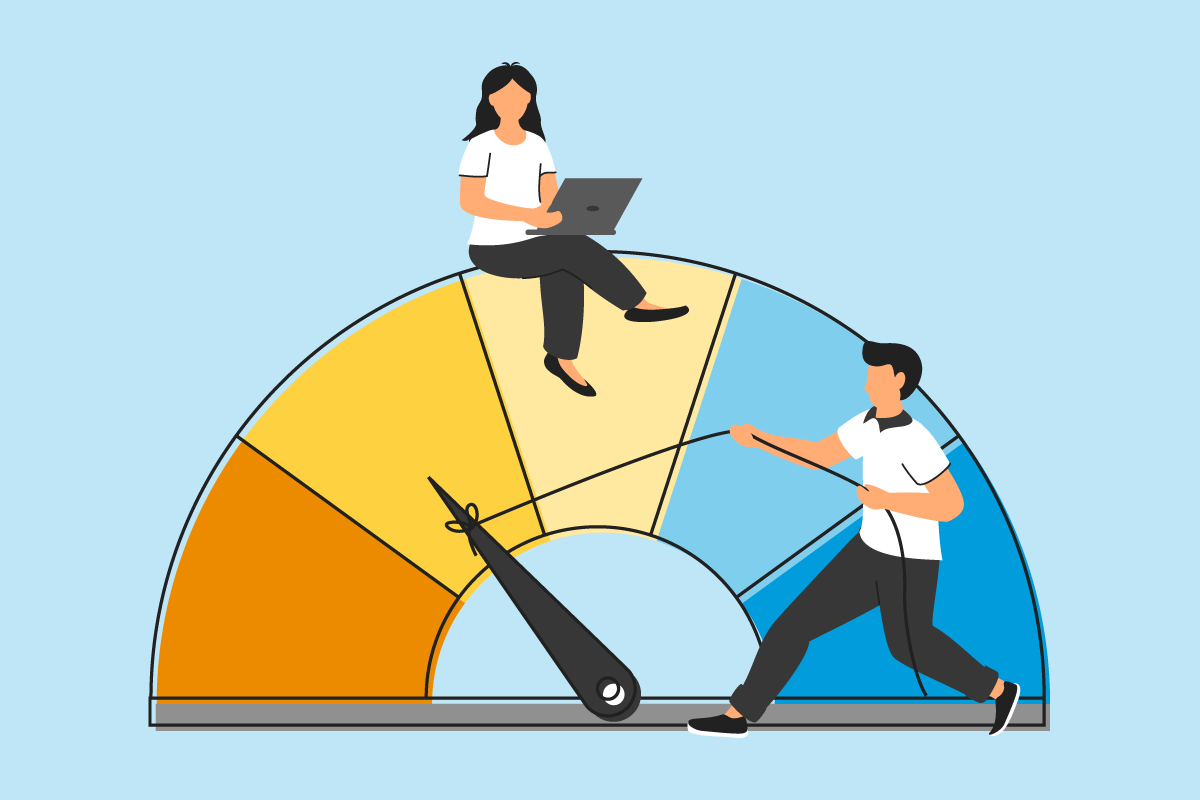
A single late payment often raises alarm bells among credit users. But the exact effects are often misunderstood. In reality, a single late payment can cause a credit score to drop by anywhere from 60 to 110 points, depending on your credit history. For example, someone with a flawless FICO score above 800 may see a bigger decline than someone with a lower baseline credit score.
Late payments appear on credit reports after 30 days past due and remain for seven years. This negative mark influences future approvals and loan terms. Imagine borrowing $300,000 for a home mortgage— a 70-point score drop can shift your interest rate by 0.5% or more, resulting in thousands extra paid over the loan lifetime.
The damage starts small but compounds quickly with longer delinquencies. Even minor delays matter, as lenders use algorithms that weigh payment punctuality heavily—nearly 35% in FICO's scoring model. This old Discover card I once used, from 2017, had a late payment that hit my score unexpectedly hard. Six months later, the mark still affected my credit access.
Late Payment Misunderstandings
Many believe a single tardy fee is minor and quickly forgotten. It's not. Some assume paying late once won’t hurt scores much or that paying before a statement closes can erase damage. Neither is true. Reporting to credit bureaus only happens monthly, typically after 30 days of non-payment.
People also mistake ""late"" for 1-5 days overdue; lenders often do not report such short delays. But once 30 days pass, the late payment gets recorded and rapidly drags your score downward. If your payment arrives on day 31, that’s when it hits the report and score.
Underestimating the long-term impact leads many into a cascade of higher rates, fewer credit offers, and a tougher financial life overall. This is especially painful for freelancers or gig workers with irregular cash flow who might skip payments mistakenly thinking a single miss won’t matter.
Fixes and Tactics
Pay on Time Or Early
Paying before due dates prevents late payment reporting altogether. Even by 5 days early, your bank logs a good payment, and credit bureaus remain clear. Using automatic bill pay services through platforms like Chase QuickPay or your bank’s app can reduce human error.
Use Payment Alerts
Set alerts on your smartphone or email through apps like Mint or Credit Karma. They notify you days before due dates, increasing your odds of timely payment. Users report a 40% drop in late payments after activating reminders; this small step cuts risk severely.
Negotiate with Creditor
If you foresee late payment, call your lender immediately. Many lenders offer hardship programs or may delay reporting a late payment for a month or more. For instance, Wells Fargo sometimes grants a 30-day grace upon request but only if you ask upfront.
Request Goodwill Removal
If a late payment occurred but your history is otherwise clean, request goodwill removal from your creditor. This is a written appeal asking lenders to delete the negative entry. Fannie Mae reports about 25% success in such cases, particularly for one-off incidents in an otherwise good history.
Build Payment History Fast
After a late payment, rebuild quickly by paying everything else on time. Use services like Experian Boost that add utility or phone bill payments to your record, showing consistent responsibility. It covers slower credit replenishment and outweighs the single negative item.
Monitor Your Credit Reports
Review credit reports regularly for errors or unresolved negative entries. AnnualCreditReport.com lets you get free copies from the big three bureaus every 12 months. Spotting and disputing inaccuracies reduces unnecessary score deductions from misreported late payments or duplicates.
Use Secured Credit Cards
If you lost good credit due to a late payment, secured cards like Capital One Secured Visa provide a safe path back. Responsible use and timely payment here restore scores. Data shows individuals using secured cards regain 100-plus points over 18 months.
Pay Down Balances Aggressively
Reducing revolving debt also helps offset a late payment’s impact. Lower credit utilization below 30% raises your score by up to 50 points quickly, which can partially offset the 50+ point dip from a late mark.
Control Multiple Accounts Independently
Late payment on one account doesn’t always spill over but aggregates into your credit risk profile. Regularly reviewing each account independently limits surprises and surprises like a forgotten subscription payment, that rarely goes reported immediately but piles up.
Real Examples
Take Jane, a 35-year-old teacher in Ohio who was 31 days late on a credit card payment in March 2023. Her score dipped from 720 to 655 within two months. She called the issuer, negotiated a goodwill adjustment after recognizing the charge was from an old subscription, and paid on time thereafter. The negative mark was removed after 45 days, and her score rebounded to 710 within a year.
John, a self-employed consultant, missed a mortgage payment in September 2022 by 33 days due to tax juggling. His credit dropped 90 points from 790 to 700. He enrolled in lender hardship and payment plans while using a secured card to build credit. In 12 months, his score climbed back to 765, but the late payment stayed visible until 2029.
Score Impact Checklist
| Factor | Effect Size | Onset | Duration |
|---|---|---|---|
| 30 Days Late | 60–110 Points | 30+ Days | 7 Years |
| 60+ Days Late | Additional 20–50 Points | 60+ Days | 7 Years |
| High Utilization | Up to 50 Points | Immediate | Varies |
| Goodwill Removal | Score Rebound Possible | Varies | Depends |
Errors to Avoid
Never ignore a late payment notice, hoping it will go away. It won't. Many skip calls from creditors, which delays resolution. Immediately assess the situation, pay if possible, or set up payment plans before reporting.
Avoid lumping all payments together. Large bills get missed often—car loans, mortgage payments must get higher priorities. Also, do not rely exclusively on credit scoring apps like Credit Sesame; they sometimes lag and show outdated info, which, frankly, most people skip verifying properly.
Don’t dispute legitimate late payments. This wastes time and irritates creditors if you have a genuine lapse. Focus on managing future payments instead.
FAQ
How quickly does a late payment affect credit?
Usually, it appears 30 days after the due date if unpaid. Scores drop as soon as bureaus receive the report, timing varies by lender.
Can a single late payment ruin my credit?
It won't ruin it, but it can lower your score dramatically—up to 110 points depending on your history.
How long does a late payment stay on my report?
Negative marks remain for seven years from the date of lateness, though their impact diminishes over time.
Is it possible to remove a late payment?
Yes, through goodwill removal requests or if errors exist. Success depends on lender policies and payment history.
What’s the best way to recover after a late payment?
Pay all other bills on time, reduce credit card balances, and consider secured credit cards to rebuild credit fast.
Author's Insight
I've watched late payment effects firsthand—both in clients' and my own credit profiles. The score plunge is swift and brutal, but recovery takes longer. Being upfront with lenders and consistent with payments afterward truly helps. Automation and alerts, tools I started using in 2019, stopped many close calls. Credit is fragile; protect it actively.
What to Remember
A single late payment can reduce your credit score 60–110 points and remain visible for seven years. Pinpointing payments, using reminders, and handling issues quickly limit damage. Once late, rebuilding through good habits and strategic credit choices restores scores slowly but surely. Don’t dismiss the hit; act fast, and credit health improves.