The Price Of Borrowing
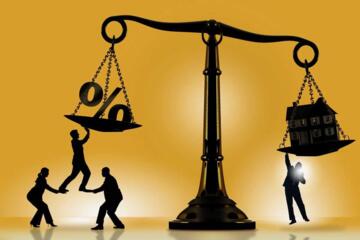
Most people focus on the size of the loan. Lenders focus on the payment.
That distinction explains why interest rates matter so much. A borrower earning $80,000 per year may qualify for a very different loan amount depending on where rates sit at the time of application.
Consider a mortgage example. In early 2021, many borrowers could find 30-year mortgage rates near 3%. By 2023, rates above 7% became common. The income of the borrower might not have changed. The house might not have changed. The payment did.
That changed everything.
When rates rise, more of each monthly payment goes toward interest. Less goes toward principal. Lenders respond by reducing the amount they are willing to lend because the borrower must remain within debt-to-income limits.
The result often surprises people. A rate increase of a few percentage points can cut borrowing power by hundreds of thousands of dollars on large loans.
Why Borrowing Power Shrinks
A common misconception is that banks simply decide how much money they want to lend. In reality, most lenders follow formulas tied to income, existing debts, credit history, and projected monthly obligations.
Mortgage lenders often examine debt-to-income ratios. Many prefer total debt obligations to remain below roughly 36% to 43% of gross monthly income, depending on the loan program.
The math becomes unforgiving fast.
Suppose a lender determines that a borrower can comfortably spend $2,500 per month on housing costs. At a lower interest rate, that payment supports a larger loan balance. At a higher rate, the same payment supports far less debt.
The borrower may feel poorer overnight despite earning exactly the same salary.
Car loans show the same pattern. A buyer shopping for a $45,000 vehicle at 4% interest faces a much different payment than someone financing the same vehicle at 8%. The vehicle has not changed. The financing environment has.
Ways To Protect Buying Power
Improve your credit score early
Higher credit scores often unlock lower interest rates. That difference may appear small on paper. It rarely feels small over 30 years.
A borrower moving from a score of 680 to 760 could qualify for noticeably better mortgage pricing depending on market conditions. Lower rates translate into larger loan eligibility and lower monthly costs.
Start 6 to 12 months before applying. Review credit reports, dispute errors, and reduce revolving credit balances.
Preparation pays here.
Reduce existing debt
Lenders look beyond the new loan. Credit card balances, student loans, personal loans, and auto financing all affect borrowing calculations.
Paying off a $400 monthly obligation may create room for a larger mortgage approval. Many borrowers focus entirely on saving for a down payment while ignoring debt reduction opportunities.
The lender sees both numbers.
Sometimes eliminating debt produces a larger approval increase than adding thousands to savings.
Increase the down payment
A larger down payment reduces the amount that must be financed. That lowers risk for lenders and improves affordability calculations.
Many buyers still believe they need 20% down. That is not always true. Conventional loans may require far less. FHA loans may require as little as 3.5% for qualified borrowers.
Still, additional cash upfront can offset some damage from higher interest rates.
Even 5% more helps.
Shop multiple lenders
Not all lenders price loans the same way. One institution may offer a rate 0.5 percentage points lower than another on the same day.
That gap matters. On a large mortgage, the difference can affect both qualification and long-term cost.
Compare banks, credit unions, online lenders, and mortgage brokers. Request loan estimates within a short window so credit inquiries are grouped together.
The savings can surprise you.
Consider shorter loan terms
Borrowers often assume shorter terms always create higher costs. Monthly payments do rise, but shorter loans frequently carry lower rates.
A 15-year mortgage may offer a better rate than a 30-year mortgage. For borrowers with strong cash flow, that difference can generate substantial interest savings.
Not everyone can support the larger payment. Some can.
Lock rates strategically
Mortgage rate locks protect borrowers from market swings during the approval process. A sudden increase during a 30-day closing period can affect affordability.
Rate locks usually last 30 to 60 days, though longer options exist.
Ignore the lock at your own risk. Markets can move quickly after inflation reports, employment data releases, or central bank announcements.
A few weeks matter.
Look beyond the monthly payment
Many buyers ask only one question: "Can I afford the payment?"
The better question is whether the payment leaves room for everything else. Property taxes, insurance, maintenance, utilities, and emergency expenses continue regardless of interest rates.
Higher rates often expose budgets that were already stretched.
Build room for surprises. Houses, cars, and life have a habit of producing them.
Real Borrower Examples
Consider a hypothetical first-time home buyer earning $95,000 annually. In a market where mortgage rates sit near 3%, the borrower qualifies for a loan large enough to purchase a $450,000 property with a moderate down payment.
Fast-forward to a rate environment above 7%. The same borrower, with the same income and similar debts, may qualify for a property closer to $325,000 or $350,000 depending on taxes and insurance.
The income never changed.
The buying power did.
A second example involves auto financing. A buyer financing $35,000 over 60 months at 3% faces a monthly payment around $629. At 8%, that payment rises substantially.
Some borrowers respond by extending the term to 72 or 84 months. The payment becomes manageable, but total interest costs climb.
That tradeoff often receives less attention than it deserves.
Quick Comparison Guide
| Rate | Payment | Power | Pressure |
|---|---|---|---|
| 3% | Lower | Higher | Lower |
| 5% | Medium | Medium | Medium |
| 7% | Higher | Lower | Higher |
Common Borrowing Mistakes
The first mistake is shopping based on home price instead of monthly payment. Borrowers become attached to a target property before confirming what current rates support.
Another mistake involves waiting for the "perfect" rate. Financial markets rarely cooperate with predictions. Many people delayed purchases during low-rate periods expecting even lower rates.
That did not work out.
Ignoring total debt is another problem. Credit cards carrying high balances can quietly reduce borrowing power. The effect becomes larger when rates rise.
Some borrowers also underestimate closing costs. Saving only for a down payment leaves little flexibility when lender fees, title charges, inspections, and taxes appear.
Finally, many people stretch to the maximum approval amount. Approval and affordability are not the same thing. A lender's limit is not a spending recommendation.
FAQ
How much can interest rates affect mortgage approval?
Even a 1% increase can reduce purchasing power noticeably. Larger increases may cut approval amounts by tens of thousands or even hundreds of thousands of dollars depending on income and loan size.
Do higher rates always mean I should wait to borrow?
Not necessarily. Home prices, income growth, inventory levels, and personal finances all matter. Waiting for lower rates may not produce a better outcome if prices continue rising.
Can refinancing help if rates fall later?
Yes. Many homeowners refinance when rates decline. The strategy may reduce monthly payments or shorten the repayment period.
Why does my credit score affect interest rates?
Lenders view higher credit scores as evidence of lower risk. Lower risk often leads to lower rates and better borrowing terms.
What loan types are most sensitive to rate changes?
Long-term loans such as 30-year mortgages typically experience the largest impact because interest compounds over many years.
Author's Insight
After years of watching lending markets, I have noticed that borrowers often focus on house prices while underestimating interest rates. The monthly payment tells the real story. I would rather see someone buy a slightly less expensive property with financial breathing room than stretch to the maximum approval. Rate environments change. Stress tends to stick around longer.
Summary
Interest rates influence borrowing power more than many people realize. Higher rates increase monthly payments, reduce loan eligibility, and change affordability calculations across mortgages, auto loans, and other forms of credit.
Improve credit early. Reduce debt before applying. Compare lenders carefully. And remember that the best loan is not always the largest one a lender is willing to approve.