Joint Accounts: The Basics
A joint account is a single bank account held in more than one person’s name, so each named holder typically has the same access rights to the funds. Banks usually treat the account as one pool of money, even though each holder may have different intentions for how it should be used. For example, two spouses might use a joint checking account for rent and utilities, while each keeps separate savings for personal goals.
In many jurisdictions, joint account ownership is not just a “shared convenience.” The legal effect often depends on the account type and the governing account agreement. Some accounts are set up as joint tenants with rights of survivorship, while others may be structured differently. The practical result is that the bank can pay out to any authorized joint holder during the account holders’ lifetimes, and the account may pass to a surviving holder after death under the survivorship rules.
Before opening a joint account, read the bank’s account terms for how it handles withdrawals, account closure, overdrafts, and death. I’ve seen people assume “joint” means “split evenly,” which rarely matches how banks process transactions. A joint account can be used unevenly, and the bank still records the balance as one number.
Common Ownership Confusions
People often assume that joint ownership means each person owns half the money. That assumption can fail in real disputes because the law and the account agreement may treat the account as fully owned by each holder for withdrawal purposes. In other words, the bank may not track “who contributed” when paying checks or processing transfers.
Another frequent misunderstanding involves debts. If one joint holder runs up overdrafts or the account is attached due to a creditor claim, the account balance may be affected even if the other holder did not cause the problem. The exact outcome depends on local law and the nature of the claim, but the risk is real enough that many families keep separate accounts for personal spending.
Supporting systems also matter. Joint accounts are usually linked to online banking, debit cards, bill pay, and automatic transfers. If a joint holder changes the bill-pay payee list or updates a direct deposit, the other holder may not notice until a payment fails. A small aside: on many bank apps, the transaction feed loads with a delay of seconds to minutes, which can make “who did what” harder to reconstruct during a dispute.
Finally, death triggers a different set of rules than day-to-day access. Survivorship provisions can cause the surviving holder to receive the account balance without waiting for probate, depending on the jurisdiction and account structure. That can be helpful for bills, but it can also conflict with a person’s estate plan.
How to Choose Safer Setups
Check Account Type And Terms
Start by confirming the exact account type the bank is opening, not just the label “joint.” Ask the bank or review the disclosures for survivorship language, withdrawal authority, and what happens on death. If the bank offers options like “joint with survivorship” versus other structures, compare them in writing. Keep the account agreement and any disclosure PDFs in a folder; a surprising number of people can’t find the paperwork later.
For practical tracking, consider setting up separate sub-accounts or separate budgeting categories, even if the bank account is joint. A joint account can still be used for shared expenses while you maintain separate records of contributions and intended use. That recordkeeping becomes relevant if a family dispute arises years later.
Plan For Withdrawals And Debts
Assume any joint holder can typically withdraw funds without the other holder’s approval. That means debit card access, online transfers, and bill pay can move money quickly. If one holder has a history of financial instability, a joint account may create avoidable risk. Some households choose a shared bill-pay account with limited balances rather than a full “everything” joint checking.
To reduce overdraft surprises, set overdraft alerts and consider turning off overdraft coverage if your bank offers it. Many banks allow you to set low-balance notifications; check whether alerts arrive by email, push notification, or both. On one major banking app I used for testing in 2024, push alerts arrived faster than email, but the email still served as a backup log.
Use Clear Records For Intent
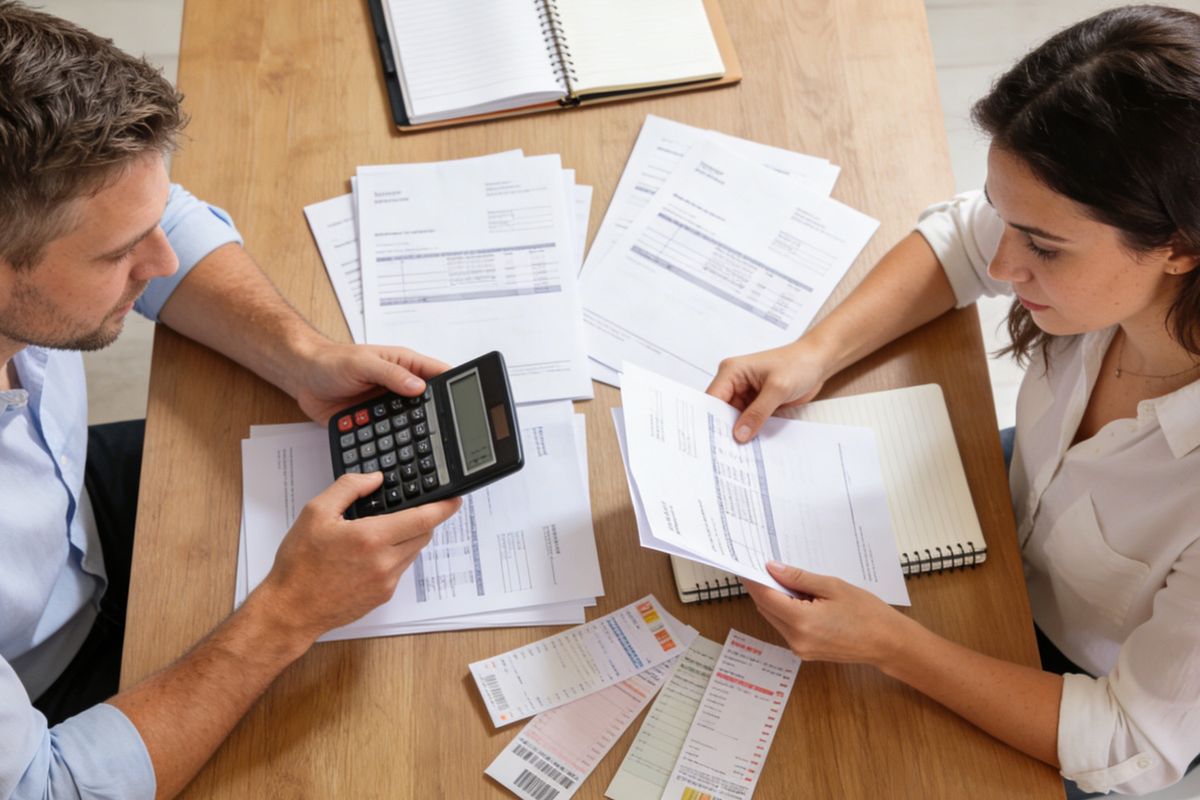
Joint access does not automatically record intent. If you want the money to be treated as shared for certain expenses, document that purpose. A simple approach is a monthly ledger: date, amount, and category (rent, utilities, groceries). If you contribute more than the other holder, record the difference so you can explain it later without guessing.
When large transfers occur—like moving savings into the joint account—write down the reason and the expected timeline. A mild frustration: banks show “transfer from X to Y,” but they do not show “transfer intended as reimbursement,” so your own notes matter.
Coordinate Estate Planning Early
Joint accounts can bypass probate for the surviving holder under survivorship rules, which can affect how an estate is distributed. If you have a will, trust, or beneficiary designations, review how they interact with the joint account. A joint account may not match your intended inheritance plan, even if you opened it for convenience.
In the United States, the legal effect of joint ownership and survivorship varies by state, and tax treatment can also vary. For decisions that involve significant assets, consult a qualified attorney or tax professional in your jurisdiction. If you do not, at least ask the bank for a written explanation of survivorship and death handling so you can plan around it.
Educational Case Examples
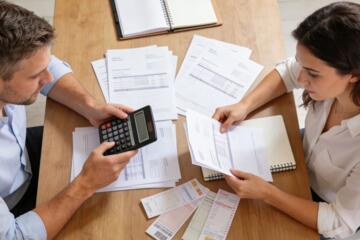
Example 1: Shared Bills, Uneven Use. Two partners open a joint checking account for rent and utilities. Partner A deposits $2,000 per month; Partner B deposits $1,000 per month. Over time, Partner B uses the account for personal purchases that Partner A did not plan for. The bank pays the transactions because both partners are joint holders. When Partner A later asks for reimbursement, the bank cannot confirm “who should have paid what,” so Partner A’s monthly ledger becomes the evidence for the intended split.
Example 2: Death and Survivorship. A parent adds an adult child as a joint holder to cover household expenses. The parent later updates a will that intends the remaining savings to go to multiple heirs. After the parent dies, the bank releases the joint account balance to the surviving joint holder under survivorship rules. Other heirs may challenge the distribution, but the bank’s payout follows the account structure. This scenario shows why estate planning needs to account for joint account mechanics, not just the will.
Decision Checklist For Joint Accounts
| Question | If Yes | Risk To Review | Practical Next Step |
|---|---|---|---|
| Do both holders need full access? | Any holder can usually withdraw and transfer. | Unplanned spending or fast movement of funds. | Use alerts, limit balances, and set spending rules in writing. |
| Could one holder face debts? | Creditor claims may reach the account. | Funds intended for shared bills may be frozen or reduced. | Keep separate personal accounts; consider a smaller shared bill account. |
| Is inheritance planning involved? | Survivorship can bypass probate. | Estate plan conflicts and family disputes. | Review will/trust with a local professional; ask the bank about death handling. |
| Do you need to track contributions? | Bank statements show transactions, not intent. | Disputes over “who paid for what.” | Maintain a simple monthly ledger and save transfer confirmations. |
Step-by-step checklist you can use before signing: (1) Read the account agreement section on withdrawals and death, (2) confirm whether the account is joint with survivorship, (3) set alert preferences for low balance and new payees, (4) decide which bills live in the joint account and which stay separate, and (5) write down your contribution plan and keep it with your records. If you skip step (2), you may learn the survivorship rules only after a death, which is a poor time to discover paperwork gaps.
Common Mistakes To Avoid
One mistake is treating a joint account as a “shared envelope” where each person’s money stays separate. Banks typically do not label funds by owner; they maintain one balance. That design makes day-to-day access easy, but it also means disputes about contributions rely on your records, not the bank’s internal tracking.
Another mistake is assuming a will controls joint account outcomes. Survivorship provisions can change who receives the balance after death. A will can still matter for other assets, but it may not override the account’s survivorship mechanics.
People also forget to update access settings. If you add a joint holder and later change your mind, removing access may require account closure or a formal change process. Some banks require both holders to sign, and some changes take days to process. A small aside: even after a change request, debit card access may remain active until the bank completes the update, which can create a window of unintended access.
Finally, many households ignore overdraft and bill-pay controls. If bill pay is set up with a joint holder’s login, that holder can add or edit payees. When payments fail, the other holder may blame the bank, but the bank often follows the instructions tied to the authorized login.
FAQ
Who Owns The Money In A Joint Account?
Each named joint holder typically has withdrawal rights over the full balance during their lifetime. The legal “ownership” for inheritance and disputes depends on the account type and local law, especially survivorship rules.
Can One Joint Holder Withdraw Everything?
Most joint accounts allow any joint holder to withdraw or transfer funds without the other holder’s approval. The account agreement and local law govern exceptions, if any.
What Happens To A Joint Account After Death?
Many joint accounts include survivorship language that lets the surviving joint holder receive the balance without probate. The exact process depends on the jurisdiction and the bank’s death-handling procedures.
Can Creditors Reach A Joint Account?
Creditors may be able to reach funds in a joint account depending on the claim type and local law. If one holder faces a judgment or levy, the account balance can be affected even if the other holder did not cause the debt.
How Do I Reduce Dispute Risk?
Use a written contribution and spending plan, keep a monthly ledger, set transaction alerts, and review the account agreement for withdrawal and death terms. For larger assets, review estate planning with a local professional.
Author's Insight
Joint accounts combine two different ideas: shared access during life and survivorship or transfer rules after death. Banks focus on authorization and account terms, not on tracking who “meant” to contribute what. Because legal outcomes vary by jurisdiction and account structure, readers should treat the bank disclosure as the primary source for mechanics and use personal records to document intent. For high-value situations, a local attorney or tax professional can clarify how joint ownership interacts with wills, trusts, and creditor rules.
Key Takeaways
Joint accounts usually give each named holder withdrawal and transfer rights over the full balance during life. Ownership for inheritance and disputes depends on the account type and local law, so read the survivorship and death-handling terms before signing. Reduce surprises by limiting the joint account to shared bills, setting alerts, and keeping a simple ledger of contributions and intended use. If estate planning or creditor risk is involved, coordinate the joint account decision with a local professional rather than relying on a will alone.